Buying a home in Cambridge is one of the biggest decisions you will ever make. It is exciting, stressful, and confusing all at the same time. There is a lot to figure out. And most of the information out there is written for people buying in Toronto or somewhere else that does not apply to you.
This guide is different. It is written specifically for people buying in Cambridge, Ontario. I will walk you through the entire process from start to finish. By the end of it, you will know exactly what to expect and what to do at each step.
Let me break it down.
Step 1: Figure Out What You Can Afford
Before you start looking at homes, you need to know your numbers. This is the boring part, but it is the most important part. If you skip this step, you are setting yourself up for disappointment later.
Start by looking at your household income, your monthly debts, and how much you have saved for a down payment. In Canada, the minimum down payment depends on the price of the home. For homes under $500,000, you need at least 5% down. For homes between $500,000 and $1,499,999, you need 5% on the first $500,000 and 10% on the rest. If the home is $1,500,000 or more, you need a full 20% down.
Here is a quick example. If you are buying a home in Cambridge for $750,000, your minimum down payment would be $50,000. That is 5% on the first $500,000 ($25,000) plus 10% on the remaining $250,000 ($25,000).
But the down payment is not the only cost you need to plan for. There are also closing costs, which I will cover in detail later in this guide.
Step 2: Get Pre-Approved for a Mortgage
Once you have a rough idea of your budget, the next step is to talk to a mortgage professional. You can go to your bank, or you can work with a mortgage broker. A broker works with multiple lenders and can often find you better rates or more options.
During the pre-approval process, the lender will look at your income, your debts, your credit score, and your down payment. They will tell you the maximum amount they are willing to lend you. They will also lock in an interest rate for you, usually for 90 to 120 days.
Getting pre-approved does two important things. First, it tells you exactly what you can afford so you are not wasting time looking at homes outside your budget. Second, it shows sellers that you are a serious buyer. When you make an offer on a home, having a pre-approval letter gives the seller confidence that you can actually close the deal.
One thing to keep in mind. Just because a lender approves you for a certain amount does not mean you should borrow that much. Your pre-approval is the maximum. You need to think about what you are comfortable paying each month. Factor in property taxes, utilities, insurance, maintenance, and all the other costs that come with owning a home.
Step 3: Find the Right REALTOR
This is where a lot of people make a mistake. They either pick the first agent they find online, or they go with someone a friend recommended without doing any research. Your REALTOR is going to be your guide through the biggest purchase of your life. Take some time to find the right one.
Find someone who knows Cambridge specifically, not just the Waterloo Region in general. Every part of this city has a different feel, different price range, and different schools. You want an agent who can explain those differences from experience.
Ask them how they communicate. How often will they update you? Will they send you new listings every day? Can you text them or do you have to call? These things matter because buying a home takes time and you need to be able to work with this person easily.
Also ask them about their process. A good agent will not just throw you into the car and start showing you homes. They will sit down with you first, learn about your situation, and put together a plan. That is how you avoid wasting time and end up in the right home.
Step 4: Start Your Home Search
Now comes the fun part. Looking at homes.
Your agent should be sending you new listings as soon as they hit the market. Cambridge has a good mix of home styles and price points, so there is usually something coming up. The key is knowing what matters most to you and staying focused on that.
Make a list of your must-haves and your nice-to-haves. Must-haves are the things you cannot live without. Maybe it is a certain number of bedrooms. Maybe it is a specific school district. Maybe it is a garage or a backyard. Nice-to-haves are the things you would love but can be flexible on. Maybe a finished basement or a newer kitchen.
When you visit homes, take notes. After the fifth or sixth house, they all start to blur together. Write down what you liked and what you did not like about each one. Rate them out of ten. This will help you compare later when it is time to make a decision.
Do not rush this step. It is tempting to jump on the first house that catches your eye. But take your time and make sure it checks the boxes that matter to you and your family.
Step 5: Know Your Cambridge Neighbourhoods
Cambridge is made up of three main communities: Galt, Preston, and Hespeler. Each one has its own feel, its own price range, and its own strengths.
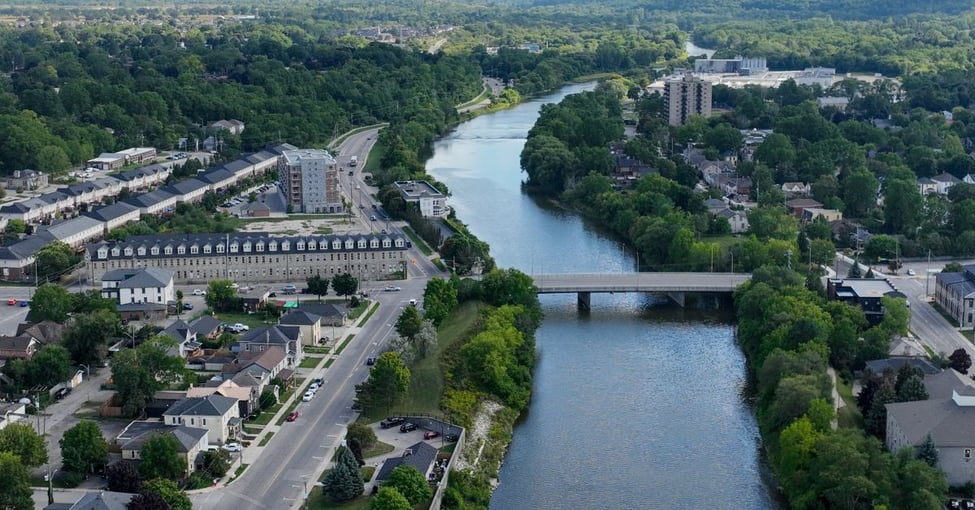
Galt is the largest of the three and is known for its historic downtown, the Grand River, and streets lined with character homes. You will find everything from stone heritage houses to newer builds on the outskirts. It has great restaurants, shops, and the Cambridge Farmers Market. Families love the trails along the Grand River and the community feel of the area.
Preston sits along the Speed River and has a strong sense of community. It is known for the Mill Race Trail, which is a beautiful walking path along the river. Preston has a mix of older bungalows, split-levels, and newer townhome developments. It tends to be a bit more affordable than parts of Galt.
Hespeler is the smallest of the three and has a village feel to it. It is also where a lot of the new construction is happening. If you are looking for a newer home or a new subdivision, Hespeler is worth a close look. It has a small but growing downtown and is close to the 401, which makes commuting easier.
Within each of these communities, there are also smaller pockets and neighbourhoods that can vary quite a bit from one street to the next. School catchment areas, pricing, and the overall feel of a street can change within just a few blocks. This is why working with someone who really knows Cambridge at a neighbourhood level matters so much.
Step 6: Make an Offer
You found a home you love. Now it is time to make an offer. This is where your REALTOR really earns their keep.
Your agent will help you figure out what the home is worth based on recent sales in the area. They will also look at how long the home has been on the market, whether there are other offers, and the condition of the property. All of this goes into deciding how much to offer.
Your offer will include a few key pieces: the price you are offering, the deposit amount, the closing date you would like, and any conditions.
Conditions are things that need to happen before the deal becomes final. The most common ones are a financing condition (giving you time to confirm your mortgage), a home inspection condition (so you can have a professional inspect the property), and sometimes a condition for the review of a status certificate if you are buying a condo or townhouse with shared fees.
In a competitive market, sellers sometimes prefer offers with fewer conditions. Your agent will help you decide what makes sense for your situation. But be careful about waiving conditions just to win a bidding war. A home inspection alone can save you from buying a money pit.
Step 7: The Home Inspection
If you include a home inspection condition in your offer (and you should in most cases), you will hire a licensed home inspector to check the property. This usually costs around $400 to $600 depending on the size of the home.
The inspector will go through the house top to bottom. They will check the roof, the foundation, the electrical system, the plumbing, the furnace, the windows, and more. After the inspection, they will give you a detailed report of any issues they found.
Not every issue is a deal breaker. Homes have wear and tear. The point of the inspection is to make sure there are no major surprises, like a failing foundation or a roof that needs to be replaced. If the inspection reveals something serious, you can negotiate with the seller to either fix it, reduce the price, or, in the worst case, walk away from the deal.
Step 8: Secure Your Financing
Once your offer is accepted and you are satisfied with the inspection, it is time to finalize your mortgage. Go back to your mortgage professional with a copy of the accepted offer. They will work with the lender to confirm the mortgage.
The lender may require an appraisal of the property. This is when they send someone to verify that the home is worth what you agreed to pay for it. If the appraisal comes in lower than the purchase price, it can create some complications. But your mortgage professional will help you work through it.
Once the lender is satisfied, they will issue a final mortgage commitment. This means your financing is confirmed and you can waive that condition on your offer.
Step 9: Hire a Real Estate Lawyer
You will need a real estate lawyer to handle the legal side of the transaction. They will review the agreement of purchase and sale, conduct a title search to make sure the seller actually owns the property and there are no issues with it, register the mortgage, and handle the transfer of funds on closing day.
Your lawyer will also calculate the adjustments. These are things like property taxes and utility costs that get split between you and the seller based on the closing date. For example, if the seller already paid property taxes for the full year but you are closing in June, you will reimburse them for the months you will be living there.
Find a lawyer who does a lot of real estate transactions. They will know what to look for and will make the process smooth.
Step 10: Understand Your Closing Costs
This is where a lot of buyers get caught off guard. The purchase price is not the only thing you are paying. There are several other costs that come due on or before closing day.
Land transfer tax. In Ontario, you pay land transfer tax based on the purchase price. It is calculated on a tiered system. On a $750,000 home, your land transfer tax would be around $12,475. First-time home buyers in Ontario can get a rebate of up to $4,000, which helps. And the good news is that Cambridge does not have a municipal land transfer tax on top of the provincial one, unlike Toronto where you pay double.
Lawyer fees. Expect to pay between $1,500 and $2,500 for your real estate lawyer, including disbursements.
Title insurance. This protects you and your lender against issues with the property title. It usually costs a few hundred dollars.
Home inspection. Around $400 to $600 as I mentioned earlier.
Moving costs. Depending on how far you are moving and how much stuff you have, this can range from a few hundred dollars to a few thousand.
Utility hookups and deposits. You may need to pay deposits when setting up new utility accounts.
Property tax and utility adjustments. As I mentioned, these get split between you and the seller.
A good rule of thumb is to budget 1.5% to 4% of the purchase price for closing costs. On a $750,000 home, that means having $11,000 to $30,000 set aside on top of your down payment.
Step 11: Closing Day
This is the day you have been waiting for. Your lawyer will handle most of the heavy lifting. They will finalize the paperwork, register the title in your name, and transfer the funds.
Before closing, make sure you have done a few things. Set up your home insurance. The lender will require proof of insurance before they release the mortgage funds. Transfer your utilities to your name at the new address. And do a final walkthrough of the property to make sure it is in the same condition as when you bought it.
On closing day, your lawyer will call you when the deal has been registered and the keys are ready for pickup. Then it is official. You own a home in Cambridge.
Step 12: After You Move In
Congratulations. You made it. But there are a few things to take care of after you move in.
Update your address with the government, your employer, your bank, and anyone else who needs to know. Set up mail forwarding through Canada Post so you do not miss anything important.
Get to know your neighbours and your neighbourhood. Cambridge has an incredible community and there is always something happening. From the farmers market in Galt to the trails along the Grand River and Speed River, there is a lot to enjoy here.
And start a small fund for home maintenance. Things will break. It is just part of owning a home. Having a little money set aside for repairs and upgrades will save you stress down the road. A good rule of thumb is to budget 1% of your home's value per year for maintenance.
A Quick Note for Families
If you are a growing family looking for more space, the home buying process can feel even more overwhelming. You might be buying and selling at the same time. You might be trying to get into a specific school district. You might be wondering if Cambridge is even the right city for you.
I get it. I moved my own family to Cambridge for a lot of the same reasons you might be considering it. More space. Better schools. A pace of life that actually lets you enjoy time with your kids.
I created the Family Forward Method specifically for families who are upsizing. It is a five-step system that covers everything from figuring out your vision for your next home to getting settled into your new community. If you are a family thinking about making a move, it is worth learning about.
Final Thoughts
Buying a home in Cambridge does not have to be confusing. There are a lot of steps, but when you take them one at a time, it is very manageable. The most important thing is to do your homework, work with people you trust, and do not rush the process.
Cambridge is a great city. Whether you end up in Galt, Preston, or Hespeler, there is something here for everyone. And once you find the right home, it is a feeling you will not forget.